

Kuwait’s merger rules extend to foreign deals despite absence of local entities
The absence of a local corporate presence does not necessarily remove a transaction from Kuwait’s merger-control requirements.
By Tijan Al Mughrabi
Dr. Yaqoub AlSanea & Partners (YYA)
Special to The Times Kuwait
Foreign companies involved in mergers and acquisitions may need to obtain prior approval from Kuwait’s Competition Protection Agency (CPA), even when neither party has a subsidiary, branch or shareholder in the country, under the wording of Kuwait’s revised merger-control rules.
The issue arises from amendments introduced through CPA Board Resolution No. 32 of 2026, which took effect on April 5, 2026. While the reforms raised the financial thresholds for merger notifications and introduced a local-sales condition for certain transactions, the condition does not apply uniformly across all notification tests.
The distinction is significant for international businesses undertaking cross-border acquisitions, as a transaction between two foreign companies may still fall within Kuwait’s merger-control framework if the relevant financial thresholds are met.
Three tests determine notification requirements
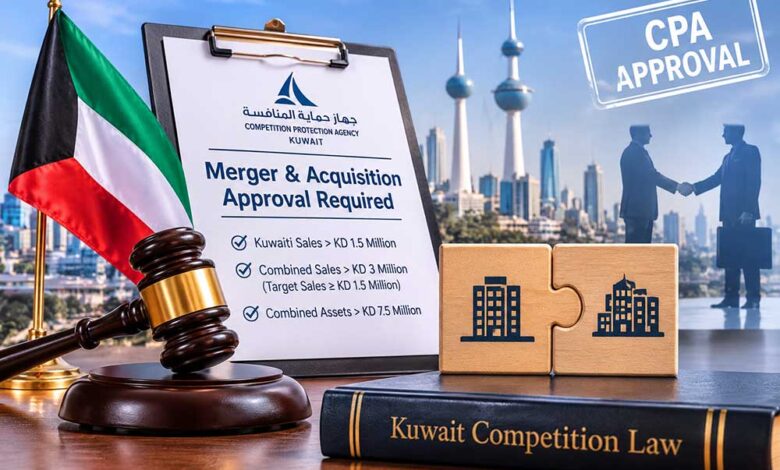
Under Article 12 of Law No. 72 of 2020 on the Protection of Competition and the 2026 resolution, transactions must be assessed against three alternative financial tests, using audited accounts for the last financial year before completion.
A notification may be required when:
- One party’s annual sales in Kuwait exceed KD1.5 million.
- The parties’ combined sales in Kuwait exceed KD3 million, provided the company or activity being acquired generates at least KD1.5 million in Kuwaiti sales.
- The parties’ combined registered assets in Kuwait exceed KD7.5 million.
The key distinction is that the target-sales condition applies only to the combined-sales test. It does not expressly qualify the single-party sales test or the combined-assets test. Consequently, a foreign buyer with sufficient sales in Kuwait may trigger the notification requirement even if the target has no Kuwaiti sales or local business presence.
Local presence is not essential
The rules focus on economic activity in Kuwait rather than the physical presence of a company.
Kuwaiti sales include revenue generated directly in the local market or through branches, subsidiaries and controlled companies. On the natural reading of the resolution, direct exports and online sales to Kuwaiti customers may also count.
Kuwaiti assets include assets registered, owned or used in economic activity in the country.
However, the resolution does not clearly address revenue channelled through independent regional distributors or how sales by a buyer’s parent and sister companies should be attributed. Such circumstances may require case-by-case assessment.
The framework covers mergers, acquisitions of direct or indirect control and joint ventures carrying out lasting, independent economic activities. Even a minority investment may constitute an acquisition of control if the investor obtains rights that provide decisive influence over the business.
Prior approval required before completion
Kuwait operates a prior-approval system rather than a regime that permits transactions to close automatically after filing. Article 14 prohibits parties from taking steps to complete a transaction before approval from the CPA Board. Silence from the authority does not constitute consent.
The review period can extend to 90 days after a complete application is referred to the Executive Director, with a possible additional 90-day extension. A separate 30-day period applies to the Board’s decision after the application is presented to it. Objections from third parties can suspend the review clock.
Failure to notify when required can attract fines of up to 10 percent of the parties’ total revenues for the preceding financial year. The law does not specify in the relevant provision whether this refers to Kuwaiti or worldwide revenues. The article also notes that other fining provisions in the same article were struck down by the Constitutional Court in 2025, while this penalty remains in force.
Implications for international businesses
The revised thresholds provide clearer financial benchmarks, but the wording leaves questions about how the target-sales condition interacts with the other tests. For companies planning cross-border transactions, the practical implication is that Kuwait should remain part of the merger-control assessment even where the buyer and target are both foreign entities.
Businesses should review each party’s Kuwaiti sales and assets, assess whether minority rights confer control, and seek legal advice where the attribution of revenue or the notification obligation is unclear.
The article recommends using the CPA’s pre-notification consultation process where necessary, allowing sufficient time for Arabic-language filings and legalised powers of attorney, and including CPA approval as a condition precedent in transaction documents whenever the relevant thresholds are met.
Kuwait’s approach underscores an important principle for international dealmakers: the absence of a local corporate presence does not necessarily remove a transaction from the country’s merger-control requirements.